Budget · Savings · Net worth · Debt · Retirement
Your money, worked out on one calm page.
You type the numbers. It shows the arithmetic: where each dollar goes, when each debt ends, and how long savings last. No bank logins, ever.
$5.99 a month or $49.99 a year · Cancel any time, your data stays yours
What it does
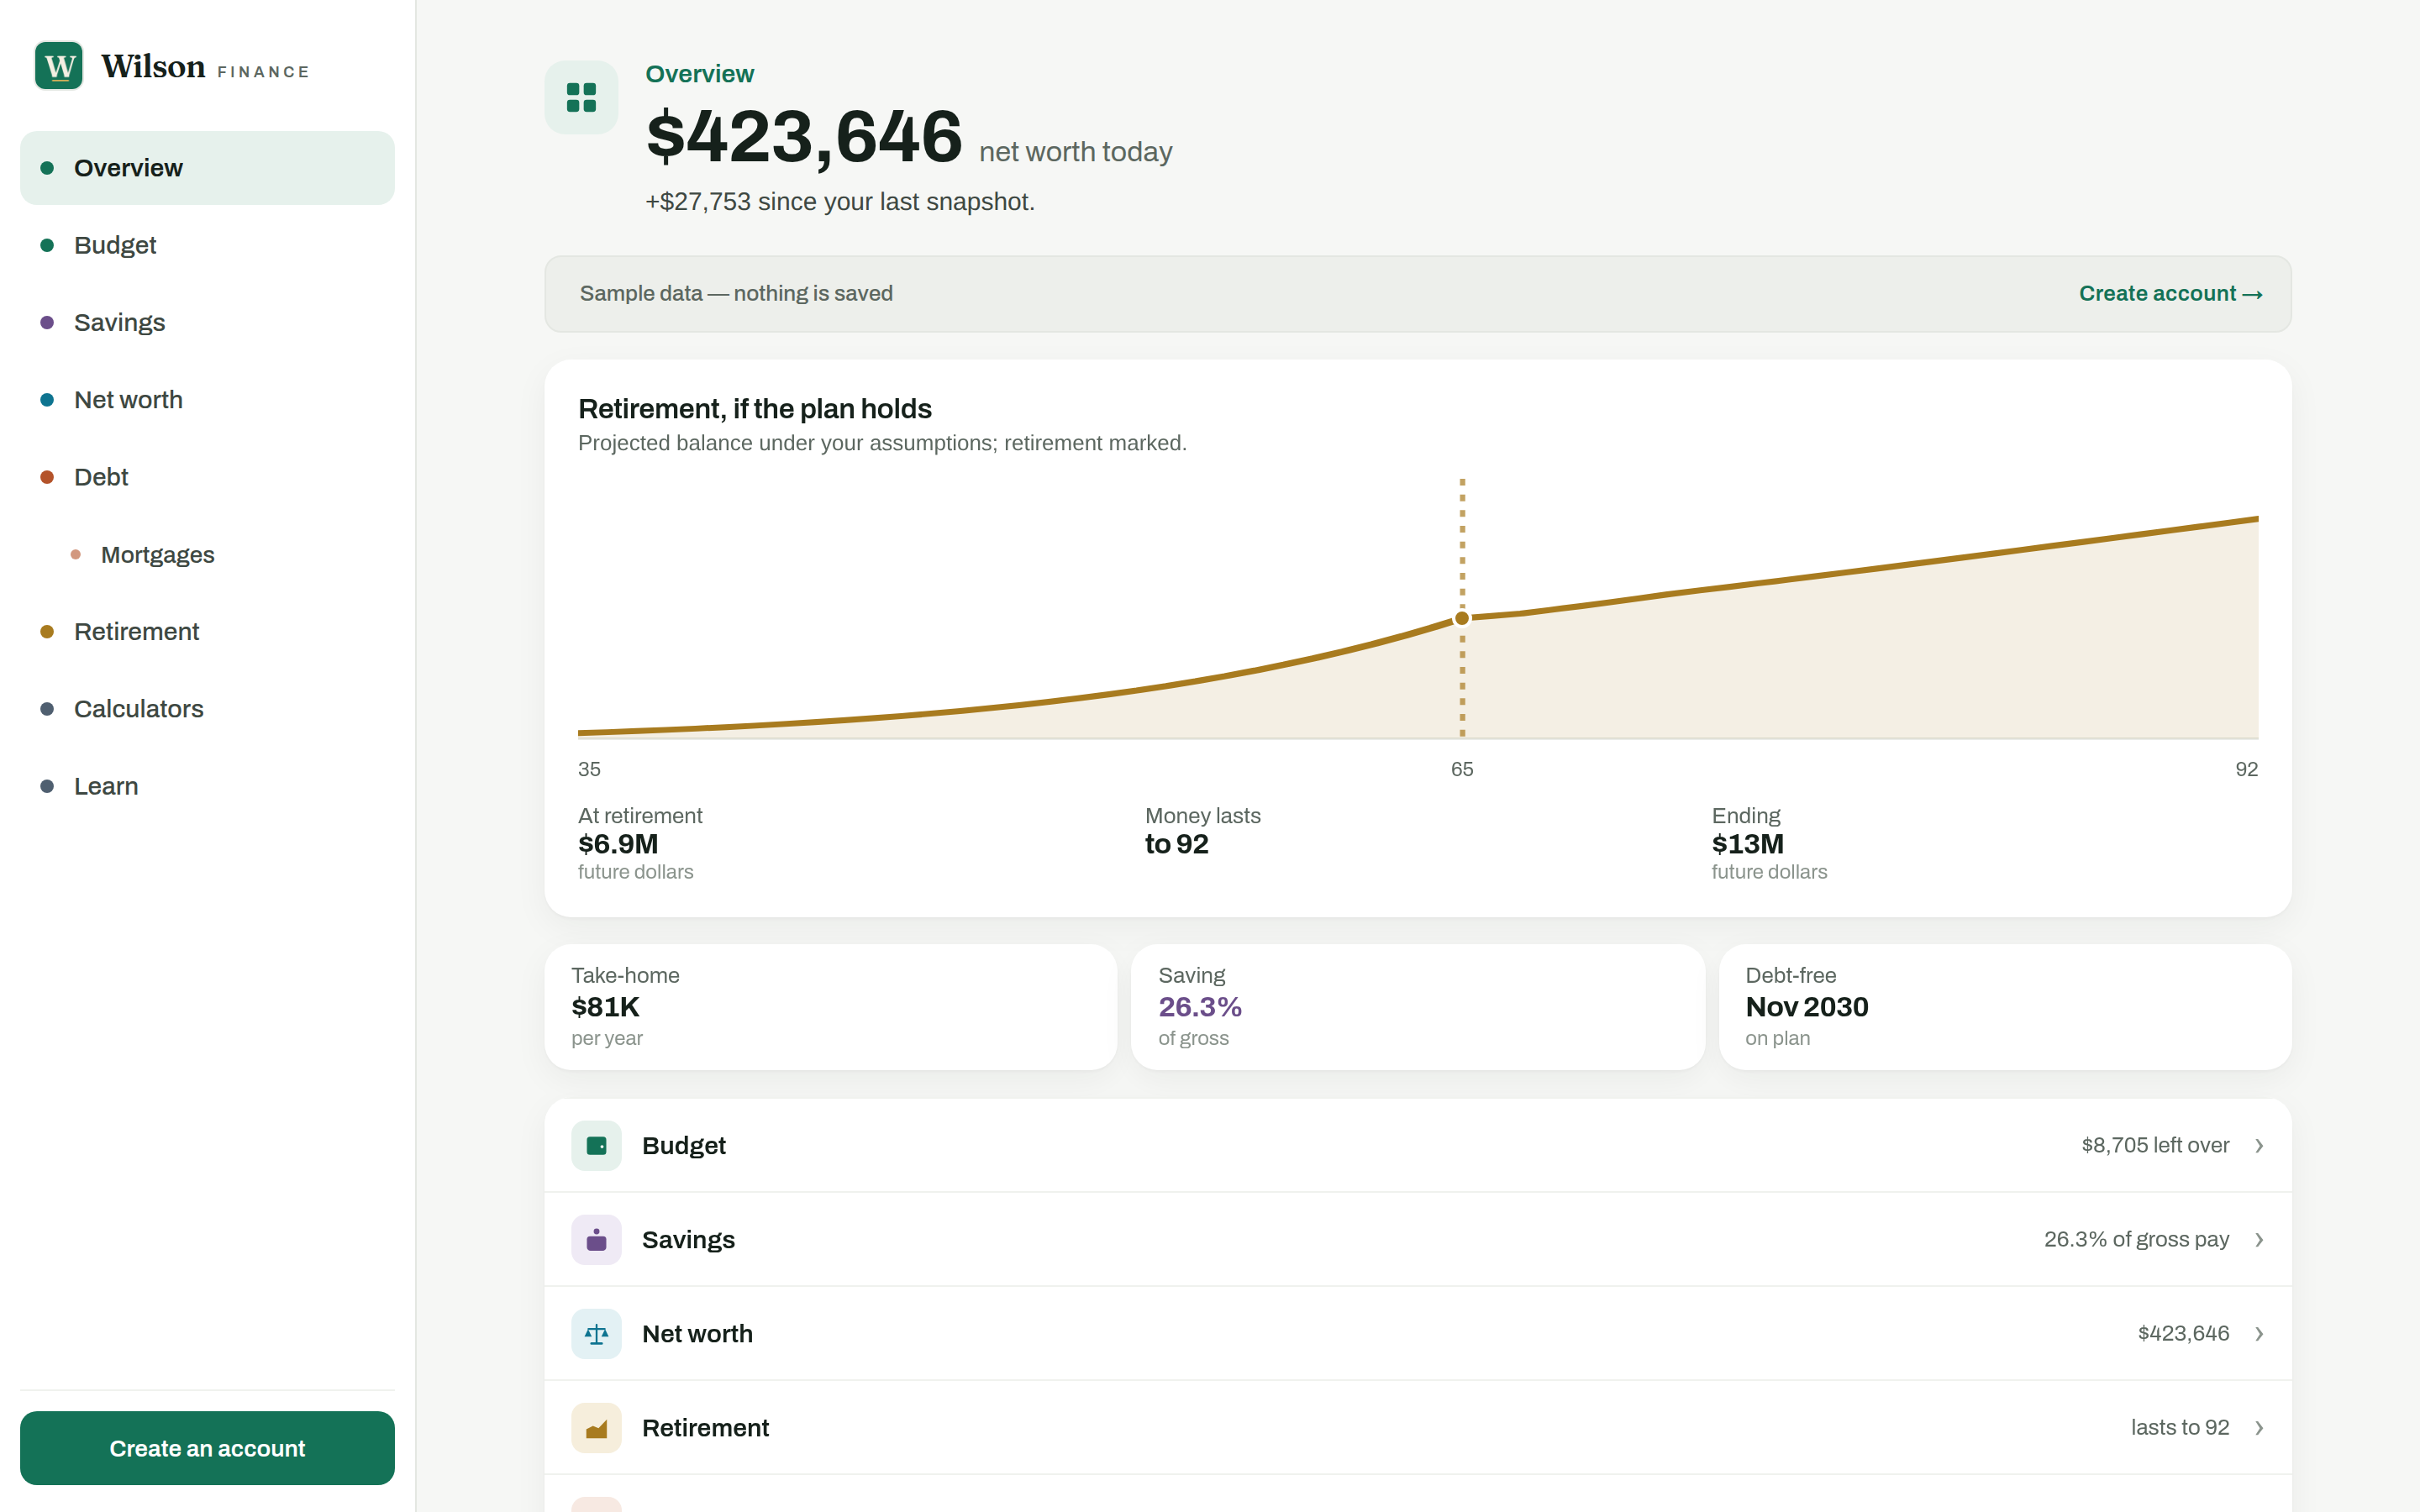
Five questions, answered with arithmetic.
Each section stands on its own. None of them needs the others filled in first, so you can start wherever your actual question is.
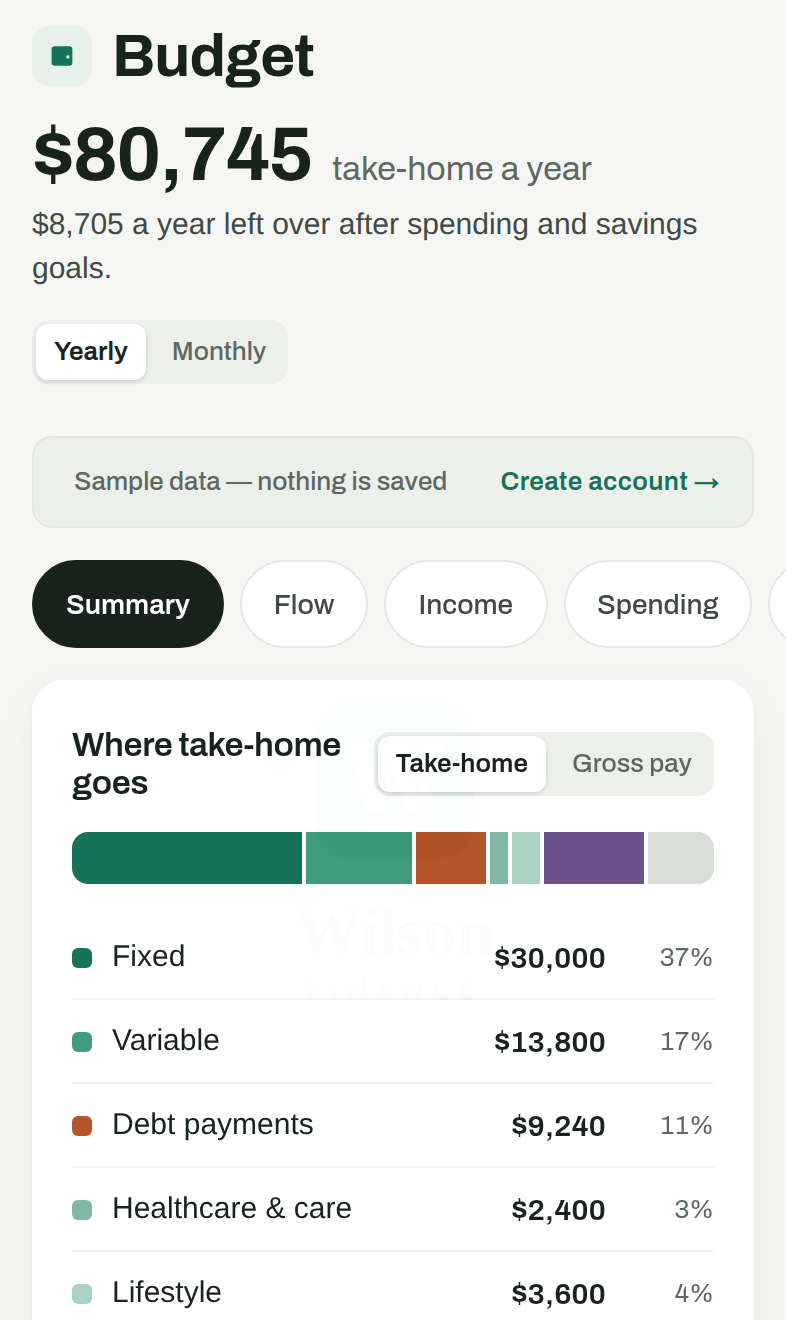
Budget
Where does the money actually go?
Enter what you earn and what you spend, and see what lands in your pocket after federal brackets, state tax, FICA, 401(k), HSA and ESPP. Two earners if you have them. Annual or monthly, same data.
- 2026 IRS brackets and standard deduction, not a flat guess
- Pre-tax and post-tax contributions handled separately, because they behave differently
- A savings rate and a leftover figure that account for both
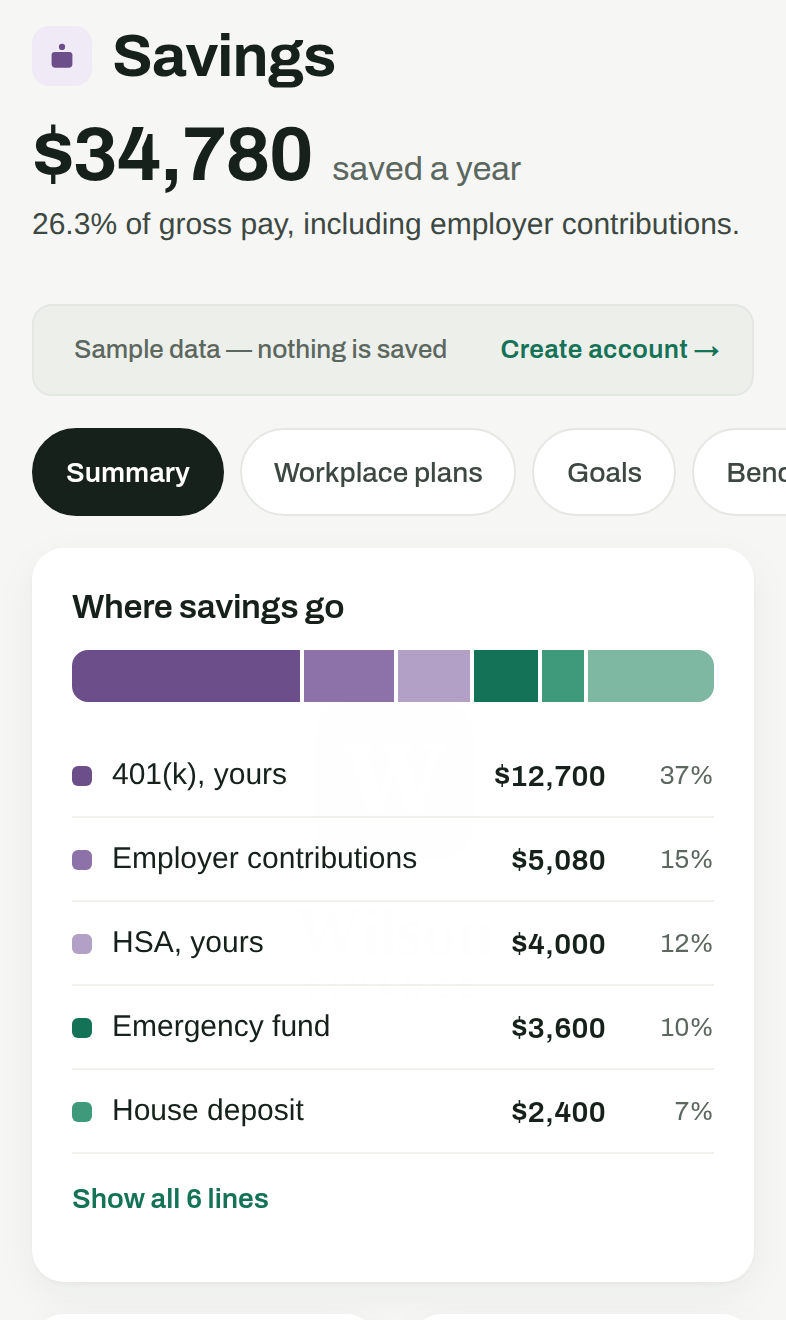
Savings
Am I saving what I think I am?
Your 401(k), HSA and ESPP contributions, your employer's match worked out from its formula, an emergency cushion, and savings goals, in one place, compared with the published limits and the benchmarks people commonly cite.
- The match your formula pays at your contribution, and at its maximum
- 2026 IRS limits for the 401(k), IRA and HSA, with the age catch-ups
- Months of essential spending your cushion covers
Net worth
What am I actually worth?
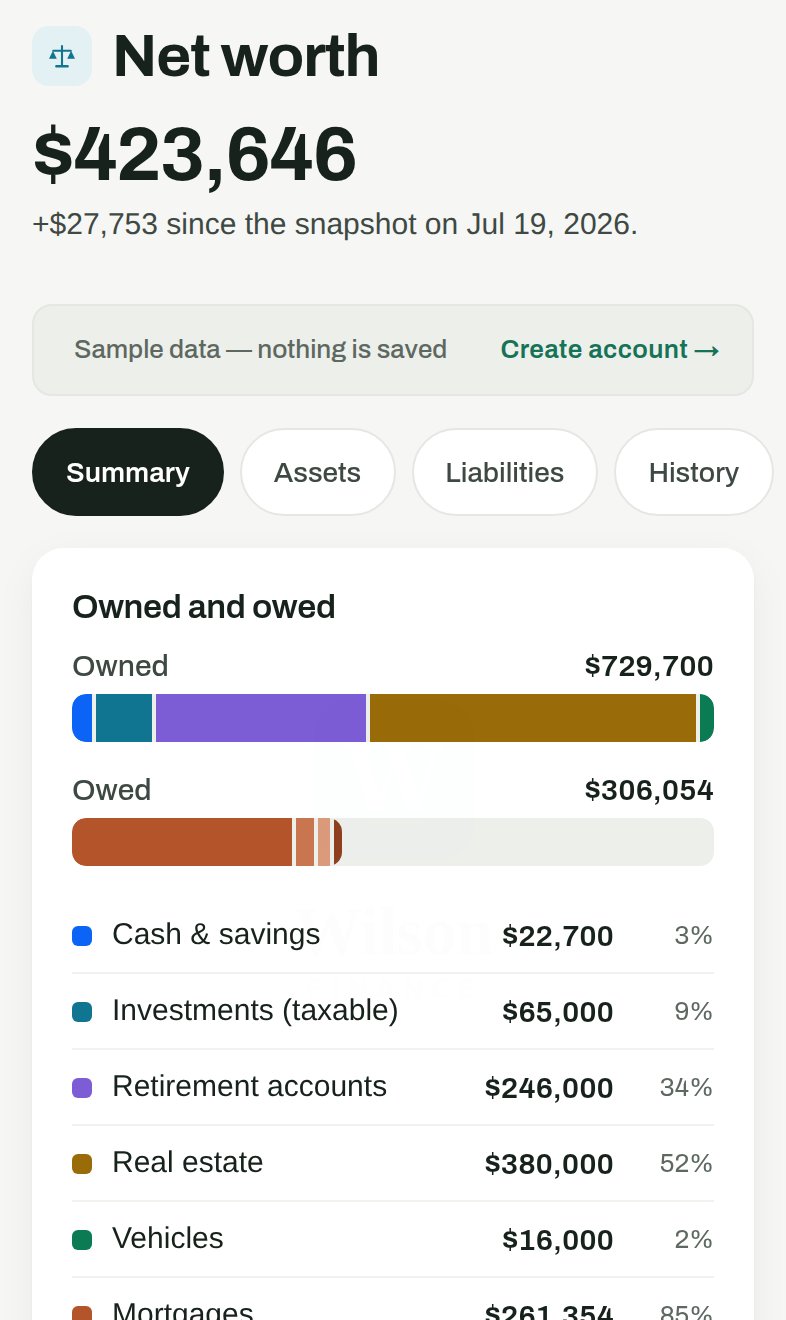
A balance sheet: what you own, what you owe, and the difference. Take a snapshot whenever you like and the trend builds itself. Pull your debts straight across from the payoff screen.
- Eleven groups across assets and liabilities
- Liquid assets tracked separately from the ones you cannot spend this month
- Dated snapshots, so the trend is history rather than a guess
Debt payoff
When am I free of this?
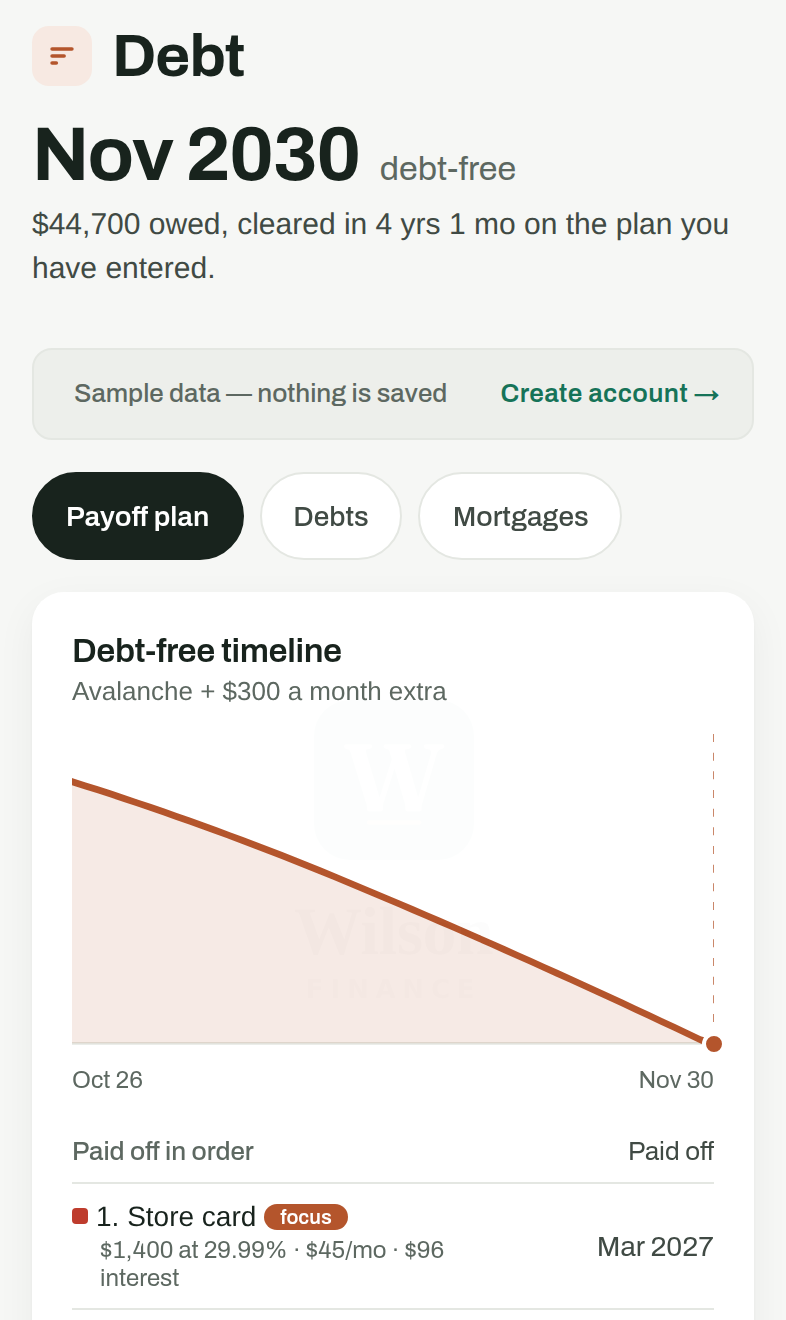
A date. Avalanche, snowball or minimums only, compared side by side with the interest each one costs, so the choice is a number rather than an opinion.
- Freed-up minimums roll forward, which is the entire point of a payoff plan
- Extra payments modelled month by month, not annualised
- The interest each strategy saves against paying minimums alone
- A mortgage analyzer: the full amortization schedule, PMI, the true rate after fees, two loans compared, and a refinance break-even
Retirement
Will this last?
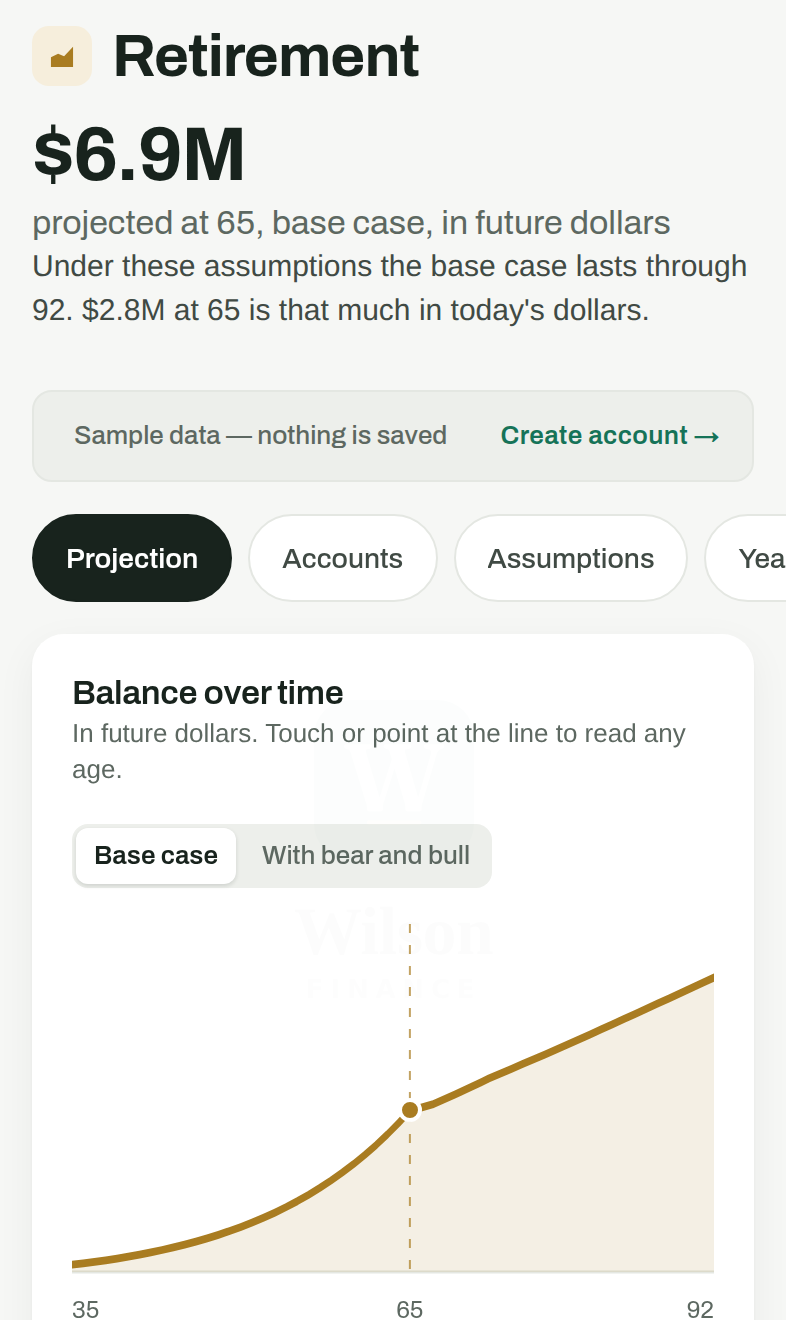
A year-by-year projection to the end of the plan: contributions, growth, taxes, required minimum distributions and withdrawals, per account, each with its own tax treatment.
- Traditional, Roth, taxable and HSA projected separately — they are taxed differently and it matters
- RMDs from the IRS Uniform Lifetime Table
- 500 Monte Carlo trials for a plan-success rate, not one optimistic line
Your data
You type the numbers in. That is the point.
Most personal-finance apps want your online banking credentials so they can categorise your transactions for you. This one does not, and will not.
No bank logins. Ever.
Wilson Finance never asks for your online banking credentials and has no connection to your bank. You type in the figures. That is slower on the first evening and it means there is no standing permission for anything to read your accounts — not us, not a data aggregator, not whoever buys one later.
Your data is yours, including after you leave.
Cancelling stops new changes being saved. It does not lock you out of what you already entered — everything stays readable. Nobody should have to keep paying to look at their own budget.
Encrypted, isolated, backed up.
Everything is encrypted in transit and at rest. Row-level security in the database means your rows are unreadable to any other account, enforced by Postgres rather than by application code that has to be right every time. Daily automatic backups.
Not sold, not shared, not advertised against.
There is no advertising in Wilson Finance and no third party is sold your financial data. The business model is the subscription; that is the whole of it.
How it is protected, including the limits, is on the security page. The legal detail is in the privacy policy.
Pricing
One subscription. Web now, iPhone soon.
Subscribe once and it works in any browser, signed in to your account. The iPhone app is coming soon and will use the same subscription. There is no free tier and no advertising: the subscription is the entire business model, which is why nothing here needs to be done with your data.
- Budget, Savings, Net worth, Debt payoff and Retirement, saved to your account
- The same plans in any browser; the iPhone app is coming soon
- Net-worth snapshots and the trend they build up over time
- Projections with real tax brackets, RMDs and Monte Carlo trials
- Holdings from your broker's positions file, without connecting to it
- Daily encrypted backups; no bank logins, ever
Billed automatically until cancelled. Cancel any time and you keep access to the end of the period you have paid for. Cancelling never deletes anything you have entered — your plans stay readable and exportable.
Wilson Finance is a planning tool, not financial, tax or legal advice. Projections are estimates based on the assumptions you enter and will not match what happens. Tax figures are simplified and do not cover every situation. Talk to a qualified professional before making decisions about your money.